You're halfway through a kitchen addition, commercial renovation, or trade contract, and the question is simple: is this job making money? QuickBooks shows invoices, deposits, payroll, and vendor payments, but the answer still isn't obvious. Your project manager has one spreadsheet, the estimator has another, and committed subcontractor costs are sitting in email threads and vendor portals.
Thank you for reading this post, don't forget to subscribe!That isn't mainly a software problem. It's a control problem. Construction accounting in QuickBooks works when your team designs the file so budgets, commitments, change orders, retainage, billings, payroll, and tax reporting remain connected from the signed estimate through closeout. Without those controls, job profitability becomes a guess.
Why Most Contractors Cannot Tell If a Job Made Money
A contractor can finish a month with cash in the bank and still lose money on an active project. The problem appears when QuickBooks shows revenue, materials, payroll, and subcontractor payments without connecting each cost to the correct job. The owner sees transactions, not dependable project economics.
The fix starts with job costing. It assigns direct and indirect costs to a specific project, allowing the contractor to compare the original bid with actual performance. Intuit's job-costing guidance for contractors describes QuickBooks Desktop Enterprise as having the most advanced job-costing capability in the QuickBooks family and notes that QuickBooks Online provides project-based job costing in Plus and Advanced.
The missing information is usually outside QuickBooks
The books often miss four control points:
- Committed costs: Approved purchase orders, subcontractor commitments, and expected material bills remain in email, field software, or vendor portals until an invoice arrives.
- Unrecorded change orders: Scope changes stay in PDFs or text messages, even though the added work changes both contract value and expected cost.
- Unreconciled retainage: Retainage receivable is buried in accounts receivable instead of tracked separately against the contract.
- Unclear overhead: Insurance, supervision, vehicles, software, bonding, and shop costs are assigned inconsistently, distorting each job's reported margin.
QuickBooks reports only what the team enters and codes. A subcontractor bill without a project creates no dependable subcontractor cost in the project report. Labor posted to a general payroll account without a job assignment makes the project margin appear higher than it is.
The control rule is simple: every cost needs a source document, project, cost code, and approval trail.
A construction accounting QuickBooks setup should enforce that rule from contract signing through closeout. Create a project for every signed contract. Tag each direct cost to that project. Update the estimate whenever an approved change order changes the scope or price. During the weekly review, compare budget, actual, committed, billed, and remaining amounts.
The owner should know whether a job is profitable before year-end tax preparation. A weekly project profitability report exposes margin problems early enough to correct purchasing, staffing, billing, or scope decisions. For contractors preparing for 2026 tax and compliance requirements, those controls also give the CPA cleaner records and a fractional CFO a reliable base for cash planning and project decisions.
Choosing the Right QuickBooks Plan for Construction
The wrong QuickBooks plan creates a control problem before it creates a software problem. If the plan cannot track each contract's income and costs, the owner cannot review margin, committed costs, change orders, or retainage with confidence. Choose the plan around the controls your team will enforce, not the subscription price alone.
QuickBooks Online Plus or Advanced is required for Projects and project-based job costing, according to Intuit's construction job-costing information. QuickBooks Online Projects is available in Plus and Advanced, not the lower tiers. A contractor who bills by project should not build core operations on a plan that cannot produce project-level profitability.
QuickBooks Online Plus is the practical entry point for many small contractors. It supports Projects, connects income and costs to a job, and provides a base for estimates, progress billing, and project reporting. The contractor-focused setup guide places QuickBooks Online Plus at $115 per month in mid-2026, so construction-ready project tracking costs more than the base product tiers. Confirm current pricing and features before subscribing.
Match the plan to the control you need
| Plan | Project Tracking | Progress Invoicing | Best Fit |
|---|---|---|---|
| QuickBooks Online Plus | Projects and job-level costs | Suitable for standard progress billing | Small contractors with one entity and a manageable project load |
| QuickBooks Online Advanced | Projects with deeper administration and reporting options | Better for recurring and higher-volume billing workflows | Growing contractors needing stronger permissions, reporting, and workflow control |
| QuickBooks Desktop Enterprise Contractor | Strong job costing and contractor-oriented reporting | Strong desktop construction workflows | Contractors who prefer installed software and need the most developed QuickBooks job-costing environment |
QuickBooks Online Advanced fits when the owner needs more administrative control, additional users, or more detailed reporting. Do not buy it because the label sounds larger. Buy it when Plus cannot support your approval, reporting, or billing workflow cleanly, and verify the current feature set with Intuit.
Desktop Enterprise Contractor suits contractors who value local installation, established desktop reports, and a construction-oriented environment over real-time cloud access. An installed system also requires clear decisions about user access, backups, collaboration, and future migration.
My recommendation: List your projects, users, billing method, payroll requirements, and reporting needs first. Then choose the least expensive plan that supports the controls you will actually enforce.
For 2026 tax and compliance work, the plan must support records your CPA can review and your fractional CFO can use for cash planning. If committed-cost tracking, structured change-order management, or native WIP reporting remains outside QuickBooks, identify that gap before month-end surprises force a larger system decision.
Building a Contractor-Specific Chart of Accounts
A contractor's chart of accounts is load-bearing infrastructure. It determines whether your job P&L explains the business or produces a pile of broad expense totals that require spreadsheet interpretation.
Before you create estimates, separate the direct cost categories that drive project profitability:
- Direct labor: Wages and related labor costs assigned to specific work.
- Materials: Separate material categories where the trade mix makes the distinction useful.
- Subcontractors: Vendor costs for subcontracted scopes, not buried in general outside services.
- Direct job expenses: Permits, disposal, delivery, small tools, and other costs tied to a project.
- Equipment: Equipment rental and other job-specific equipment costs.
A generic account named “Job Costs” hides the exact problem you need to solve. Drywall, fasteners, cleanup, and delivery can all land in that account while the owner has no way to determine whether labor productivity or material purchasing caused the margin loss.
Keep overhead out of direct job costs
Overhead belongs in separate accounts. Vehicle costs, shop expenses, software subscriptions, bonding, licenses, insurance, office payroll, and administrative costs should remain visible as business overhead unless your accounting policy deliberately allocates them to jobs.
At month-end, you can apply a consistent allocation method based on the cost drivers that make sense for your company. The important point is consistency. A labor-heavy project and a material-heavy project shouldn't receive arbitrary allocations that make their margins impossible to compare.
Use a numbering structure that leaves room for growth:
- 1000s: Revenue
- 2000s: Cost of goods sold
- 5000s: Direct job costs
- 6000s: Overhead
- 8000s: Other income and expenses
Don't build an account for every vendor, tool, or minor material. A contractor's reports become harder to use when the chart is overbuilt. Keep the structure detailed enough to answer management questions, but simple enough that employees can code transactions consistently.
For help designing the foundation, use this chart of accounts setup resource. Your cost codes should mirror the way you estimate and manage work, not merely reproduce your vendor list.
Every direct account will eventually feed a project report. Clear names now save reclassification work later.
Setting Up Job Costing the Right Way
Job costing becomes useful only when your team assigns costs at the transaction level. Turning on a Projects feature without enforcing coding rules creates a more attractive version of the same unreliable books.
Begin with the contract, not the bank feed. Enable Projects in QuickBooks Online, then create one project for every signed contract before expenses, bills, or payroll hit the ledger. Give the project a consistent name and connect the correct customer, estimate, billing terms, and responsible manager.
Build the workflow around the work breakdown structure
Your cost-code list should mirror the work breakdown structure used in estimating and field management. A vendor list tells you who sold something. A cost-code structure tells you what the purchase accomplished.
Assign project tags or classes to:
- Labor and employee time
- Materials and supplier bills
- Subcontractor invoices
- Equipment rentals and usage
- Permits, fees, disposal, and other direct job expenses
- Allocated overhead, when your policy requires it
Require field employees and foremen to code time before payroll runs. A payroll register can be accurate for tax purposes and still be wrong for job costing if hours are assigned to the wrong project. Likewise, don't approve a subcontractor invoice until it has a project attached.
The recurring control is a weekly Project Profitability report. Compare the original budget with actual costs, approved changes, billed revenue, and known commitments. QuickBooks guidance from Miter's job-costing workflow recommends enabling Projects first, assigning costs to each project, and reviewing project-level profitability regularly. For a broader implementation perspective, the Lucentive construction accounting implementation guide is useful when your processes need to connect accounting with construction operations.
Friday control: Review the five jobs with the largest unfavorable variance before the next draw is submitted.
| Cost Code | Budget | Actual | Remaining | % Used |
|---|---|---|---|---|
| Direct labor | Budgeted amount | Posted labor | Budget less actual | Actual divided by budget |
| Materials | Budgeted amount | Posted supplier costs | Budget less actual | Actual divided by budget |
| Subcontractors | Budgeted amount | Posted subcontractor bills | Budget less actual | Actual divided by budget |
| Equipment | Budgeted amount | Posted equipment costs | Budget less actual | Actual divided by budget |
| Permits and fees | Budgeted amount | Posted direct fees | Budget less actual | Actual divided by budget |
The construction job costing overview provides useful background, but the operating rule is straightforward: no project tag, no complete margin report.
Progress Invoicing, Retainage, and Change Orders
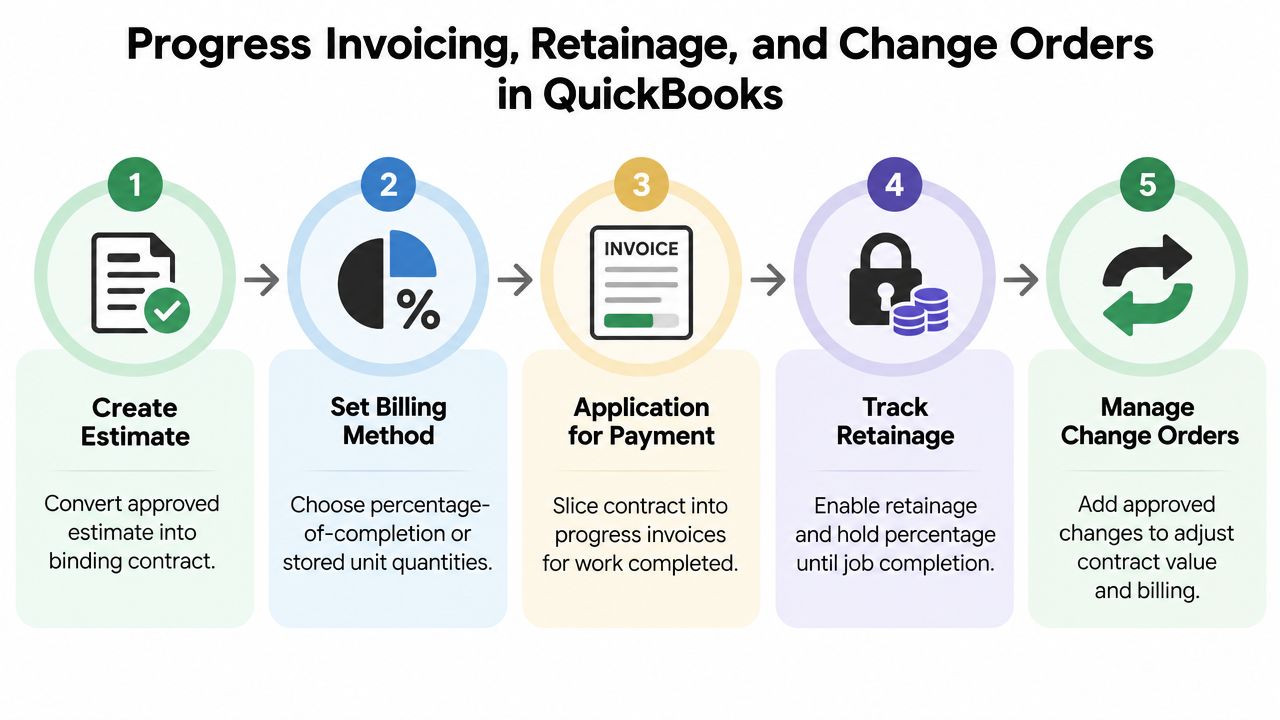
Progress billing works best when the estimate becomes the financial spine of the contract. Create the estimate before billing, convert the approved scope into a contract structure, and connect each invoice to the same project. That keeps revenue, budget, and customer billing aligned rather than creating separate numbers in separate systems.
Choose the billing method that matches the contract. Some projects use percentage of completion, while others bill stored unit quantities or defined milestones. QuickBooks can support standard progress draws, but it doesn't replace the contract review or the judgment required to determine whether the billing reflects completed work.
Treat retainage as a separate balance
Retainage should appear as a distinct line on the invoice and remain identifiable until release. Don't let it disappear into a general accounts receivable balance. The accounting treatment must match the contract and your CPA's policy, including whether the amount is recorded as a receivable, liability, or another balance appropriate to the transaction.
Change orders need the same discipline. Add an approved change as a new estimate line tied to the existing project. Record the revised cost and contract value, preserve the approval documentation, and make sure the updated estimate flows into billing. A verbal request from an owner isn't a recognized change order in your accounting system.
Know where QuickBooks stops
Standard QuickBooks workflows can handle estimates, invoices, customer payments, and basic project tracking. The system still lacks native committed-cost tracking, a structured change-order workflow, and native WIP reporting in standard tiers, according to independent construction accounting guidance from Premier Construction Software.
That gap matters because vendor bills often arrive after the cost has already been committed. Your close checklist should therefore include open purchase commitments, approved but unbilled changes, retainage balances, unbilled costs, and the revenue-recognition schedule. You may need a construction-specific extension or a controlled spreadsheet process, but the reconciliation must have an owner and a deadline.
The following video provides a visual walkthrough of related QuickBooks billing workflows.
Payroll, Certified Reporting, and 2026 Compliance
Construction payroll is where a clean job-costing design can fail quickly. Employees need project and cost-code assignments, payroll needs correct wage treatment, and the company needs records that support tax filings and contract reporting. QuickBooks Payroll can be part of the solution, but it won't decide whether your rates, classifications, fringes, and project allocations are correct.
Set up employees as W-2 workers with the correct job assignments. Collect time by project before payroll processing, reconcile labor charged to jobs against the wage register, and review burden costs separately. For government and prevailing-wage work, certified payroll and union requirements often require third-party tools or offline processing.
The 2026 reporting rules require updated vendor controls
The 2026 compliance environment changes how small businesses track contractor payments. Forms 1099-NEC and 1099-MISC move from the old $600 threshold to $2,000, while the 1099-K threshold returns to $20,000 and 200 transactions, according to the 2026 small-business compliance summary from 1-800Accountant. Those rules make vendor records, payment methods, and year-end review more important.
Qualified tips and overtime compensation must also be separately reported on Form W-2, and the maximum net self-employment earnings subject to the Social Security portion of self-employment tax is $184,500 for 2026, according to Thomson Reuters' 2026 tax compliance guidance.
| Item | 2026 Threshold or Rule | QuickBooks Action |
|---|---|---|
| 1099-NEC and 1099-MISC | Threshold rises to $2,000 | Maintain complete vendor payment records and review reportable payments before filing |
| 1099-K | $20,000 and 200 transactions | Reconcile payment processor reports to deposits and books |
| W-2 reporting | Qualified tips and overtime reported separately | Review payroll mapping and year-end wage reporting |
| Self-employment tax | Social Security earnings maximum is $184,500 | Give the tax preparer complete owner compensation and income records |
For a practical explanation of documentation and filing responsibilities, review these certified payroll reporting requirements. Certified payroll, union rate handling, retainage, and subcontractor compliance frequently require add-ons such as specialized construction payroll services. Your bookkeeping system should make those tools reconcile cleanly, not create another isolated data silo.
When QuickBooks Is Not Enough and Fractional CFO Helps
QuickBooks is an accounting core. It isn't a substitute for construction financial leadership.
Once a contractor manages multiple active jobs, the decisions become larger than transaction entry. Management needs WIP schedules, percentage-of-completion analysis, bond-capacity reporting, surety underwriting packages, cash forecasting, and explanations for margin changes. Standard QuickBooks tiers still lack native WIP, committed-cost, and structured change-order controls, so someone must design the workarounds and review the results.
The 2026 tax changes belong in the operating calendar
Construction businesses also need to account for major 2026 tax changes. Qualifying equipment placed in service after January 19, 2025, regained 100% bonus depreciation. The Section 179 expensing limit increased to $2.5 million, with a phaseout beginning at $4 million, and the 20% qualified business income deduction became permanent for pass-through entities, according to Wiss' 2026 construction tax guidance.
Those rules affect equipment purchases, entity planning, estimated taxes, and year-end timing. They don't belong in a last-minute tax conversation after the books are closed. Your CPA and fractional CFO should evaluate the accounting records, fixed assets, owner compensation, and projected taxable income during the year.
Choose the level of help your business actually needs
| Capability | DIY + QuickBooks | Construction Bookkeeper | Fractional CFO |
|---|---|---|---|
| Transaction entry | Owner or office staff | Maintains coded books and reconciliations | Reviews whether the process supports decisions |
| Job costing | Often inconsistent | Establishes projects, cost codes, and reports | Uses results for pricing, forecasting, and margin control |
| Payroll compliance | Basic setup risk | Coordinates payroll records and filings | Designs controls and escalates regulatory exposure |
| WIP and revenue recognition | Usually manual | Prepares support schedules | Interprets results and advises management |
| Cash planning | Bank balance focused | Historical reporting | Forward-looking cash and project planning |
| Surety and lender reporting | Owner assembled | Prepares schedules | Explains performance and supports underwriting |
A bookkeeper keeps the records usable. A construction accountant connects job costs, payroll, billing, and reconciliations. A fractional CFO turns those numbers into decisions about bids, staffing, equipment, collections, backlog, and growth. Every company may not need a full-time CFO, but every growing contractor needs someone accountable for financial direction.
Start with four actions:
- Correct the WIP support: Reconcile active jobs, billed amounts, costs incurred, and remaining work.
- Reconcile prior job margins: Identify which closed jobs were profitable and which coding failures distorted the result.
- Set a 2026 close calendar: Schedule weekly project reviews, monthly closes, payroll reconciliations, tax checkpoints, and year-end vendor reviews.
- Book a fractional-CFO discovery call before year-end: Decide who owns the controls before the next busy season exposes the gaps.
Bookkeeping and Accounting of Florida Inc. helps contractors set up and maintain QuickBooks, organize job costing, support construction payroll and tax compliance, and produce financial reports that owners can use. Visit Bookkeeping and Accounting of Florida Inc. to discuss a construction accounting setup, ongoing bookkeeping, or fractional CFO support for your company.